IRS Penalty Abatement:
Penalty Relief Guidance for Taxpayers
Who This Service Is Typically For
- Individuals with IRS balances or notices
- Small Business Owners
- Taxpayers Behind on Filing or Payments
If questions come up as you read, additional guidance is available when needed.
Ask a Tax Resolution Specialist:
We will get back to you as soon as possible.
Please try again later.
IRS Penalty Abatement:
How to Request Penalty Relief
IRS penalty abatement is relief that reduces or removes certain tax penalties, such as those for filing or paying late. It applies to penalties, not to the underlying tax.
What Is IRS Penalty Abatement, and Which Penalties Does It Cover?
Penalty abatement asks the IRS to reduce or remove penalties when you qualify. It commonly applies to failure-to-file, failure-to-pay, and failure-to-deposit penalties, but not to the tax itself.
A failure-to-file penalty applies when a return is late. A failure-to-pay penalty applies when tax is not paid on time. Businesses may also face a failure-to-deposit penalty for late payroll tax deposits.
When a penalty is removed, the interest charged on that penalty is removed too. Interest on the tax itself is not.
Penalties can add up quickly, so relief can meaningfully lower a balance before you choose a payment option.
Penalties are calculated on the unpaid tax, so the longer a return or payment is late, the larger the penalty grows. Knowing which penalty applies helps you decide which kind of relief to request.
Other penalties, such as accuracy-related penalties after an audit, follow different rules and may call for a different approach.
How Do First-Time Abatement and Reasonable Cause Work?
First-time abatement is based on a clean penalty history. Reasonable cause is based on circumstances beyond your control that kept you from filing or paying on time.
- First-time abatement. Generally available when you have no recent penalties, have filed all required returns, and have paid or arranged to pay the tax owed.
- Reasonable cause. Examples include serious illness, a death in the family, a natural disaster, or being unable to obtain records. You must show you acted responsibly.
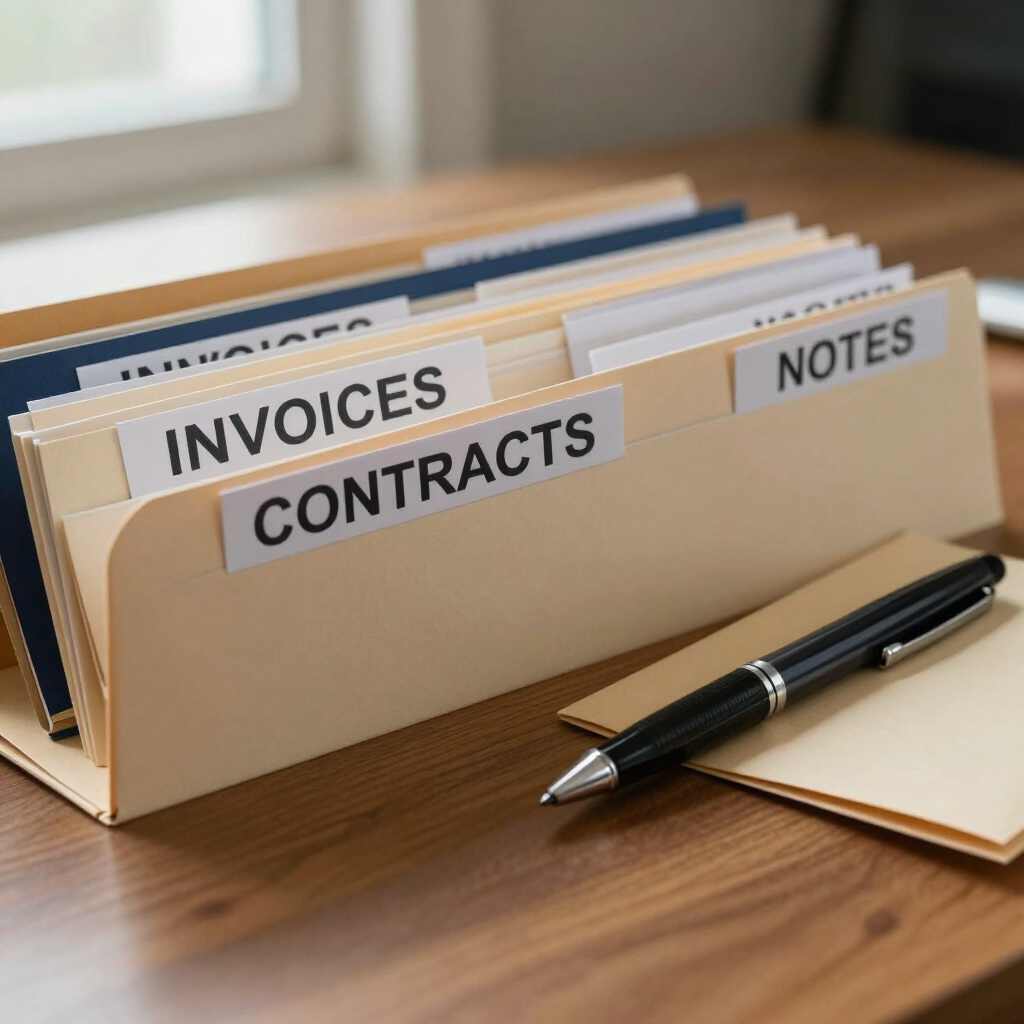
Documentation matters. Records such as medical letters, dates, and correspondence help show what happened and when, and a clear timeline makes a request easier to evaluate.
First-time abatement is often the simplest path, because it depends on your compliance history rather than your story. If you do not qualify, reasonable cause lets you explain what happened and why.
A strong request is specific. It explains what happened, when it started and ended, and what you did once the situation allowed. Vague statements are easier to deny than clear, documented ones.
How Do You Request Relief, and What Does It Not Do?
You request abatement by phone, in writing, or by form, with an explanation and supporting documents. Relief is not automatic, and it does not reduce the tax itself.
If the IRS denies your request, you have the right to appeal through the IRS Office of Appeals.
It is usually best to request relief once the underlying returns are filed and the tax is paid or arranged, because the IRS looks at compliance first. For business owners, penalties can come from late payroll deposits or late business returns, and the same principles of clear explanation and documentation apply.
Abatement does not reduce the tax you owe, and interest on the tax continues. It is not guaranteed. It is often combined with other steps, such as filing missing returns, setting up a payment plan, or answering a notice.
RQ Tax Resolution
reviews your penalties, identifies which relief may apply, and prepares the request accurately.
Frequently Asked Questions
What penalties can the IRS remove?
Commonly failure-to-file, failure-to-pay, and failure-to-deposit penalties. The tax itself and the interest on it generally are not removed.
Does first-time penalty abatement work every time?
No. It is available when you meet the IRS’s requirements and is not guaranteed. Reasonable cause may still apply if first-time abatement does not.
What counts as reasonable cause?
Circumstances beyond your control, such as serious illness, a death in the family, or a disaster. You must also show you acted responsibly once the problem ended.
What happens if the IRS denies my request?
You can appeal through the IRS Office of Appeals. A well-documented explanation strengthens that appeal.
Can I request abatement after I’ve already paid the penalty?
In many cases, yes, through a refund claim. Time limits apply, so act promptly.
Have Questions About Your Situation?
If penalties have added to your IRS balance and you want to know whether relief may apply, contact RQ Tax Resolution and speak with an expert about your options. A clear conversation about your situation is a practical first step.